Cyprus fintech sector nears 200 companies as digital finance brings new demands
Preliminary research presented at a Limassol summit shows payments dominate Cyprus’ fintech industry, as speakers examine regulation, digital assets and consumer needs.
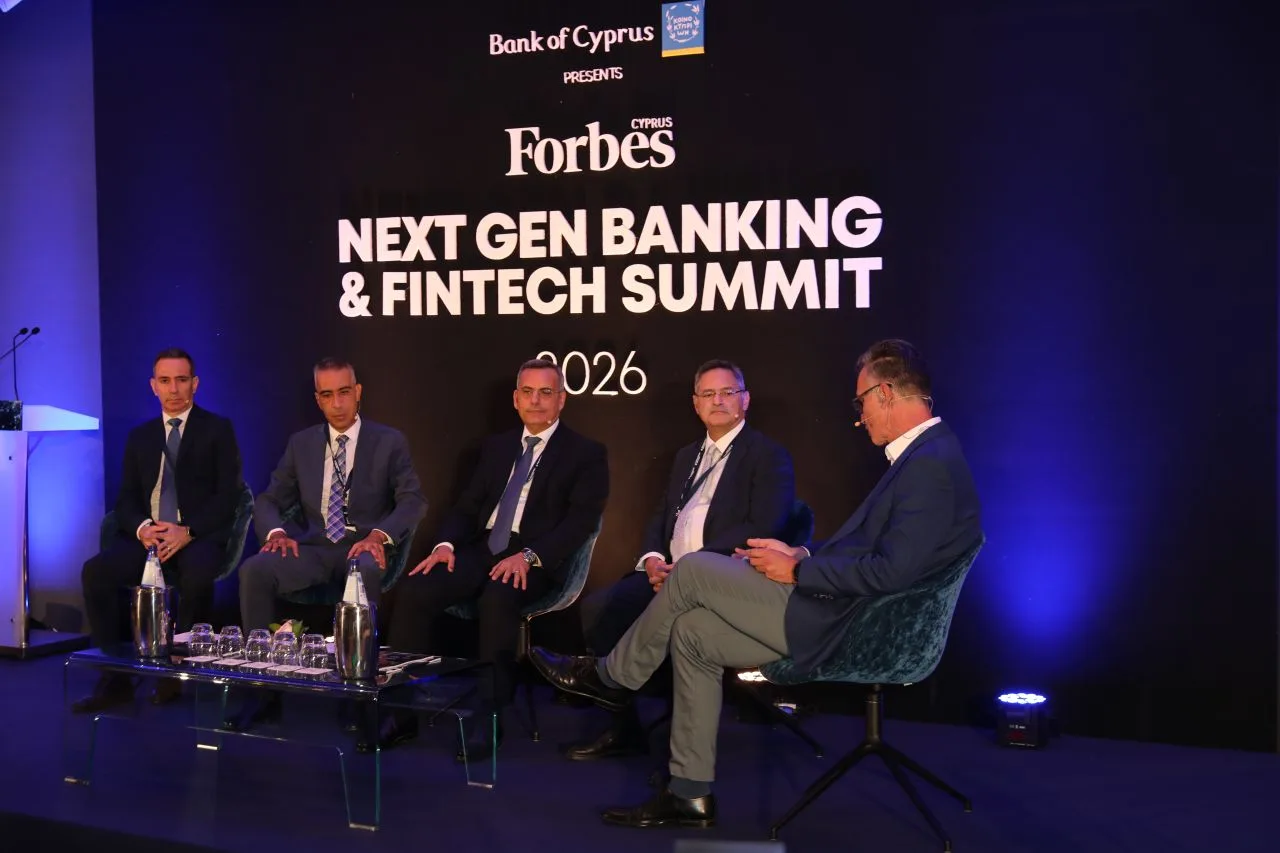
Limassol, Cyprus. Cyprus has nearly 200 fintech companies, about 55 per cent of which operate in payments, according to preliminary research presented at a summit this week. Participants discussed how expanding digital finance is increasing demands on regulation, cybersecurity and financial institution leaders.
Payments dominate the sector
European University Cyprus professor Pieris Chourides presented the findings at the Forbes Cyprus Next Gen Banking & Fintech Summit. He said companies from India and elsewhere were choosing Cyprus as an entry point into the European Union because of its regulatory framework and skilled workforce.
The research provided a starting point for representatives of Kraken, Nuvei and Bank of Cyprus (BoC) to examine potential uses of digital assets, stablecoins and emerging payment systems for consumers and businesses.
Regulation and practical applications
Alexia Theodorou, head of Kraken Cyprus, said the company had assessed several jurisdictions before selecting the island for its European base. Clear rules and the ability to communicate directly with authorities had helped shape that decision, she said.
Theodorou highlighted tokenisation, through which assets including shares can take digital form, as a means of supporting trading at any hour and creating additional services. However, she said technology should deliver practical value rather than be adopted merely because it exists.
She identified potential applications in Cyprus’ tourism industry, where businesses serving international customers could benefit from quicker settlement, reduced transaction costs and payment automation.
Kraken has also supported education in finance and technology in Cyprus. As previously reported, the company and its parent, Payward, awarded scholarships this week to six postgraduate students at the University of Cyprus: three studying finance and three studying data science.
Consumer needs and banks’ role
Laura Miller, chief revenue officer and global head of eCommerce at Nuvei, said initial predictions that cryptocurrencies would become an everyday payment method for all purchases had been exaggerated. For consumers, she said, speed and security mattered more than the underlying technology.
She pointed to digital wallets and contactless payments as products whose convenience had encouraged adoption. Stablecoins could support international transfers and broaden access to financial services, she said, but consumer protection and accountability would need to develop alongside them.
George Koushis, BoC’s executive director of technology and operations, said traditional lenders were examining both tokenisation and stablecoins. Banks could combine innovation with financial resources, experience of regulation and established relationships with customers, he said.
This news item was generated automatically by Cyprus Inform from publicly available materials. Report an error →